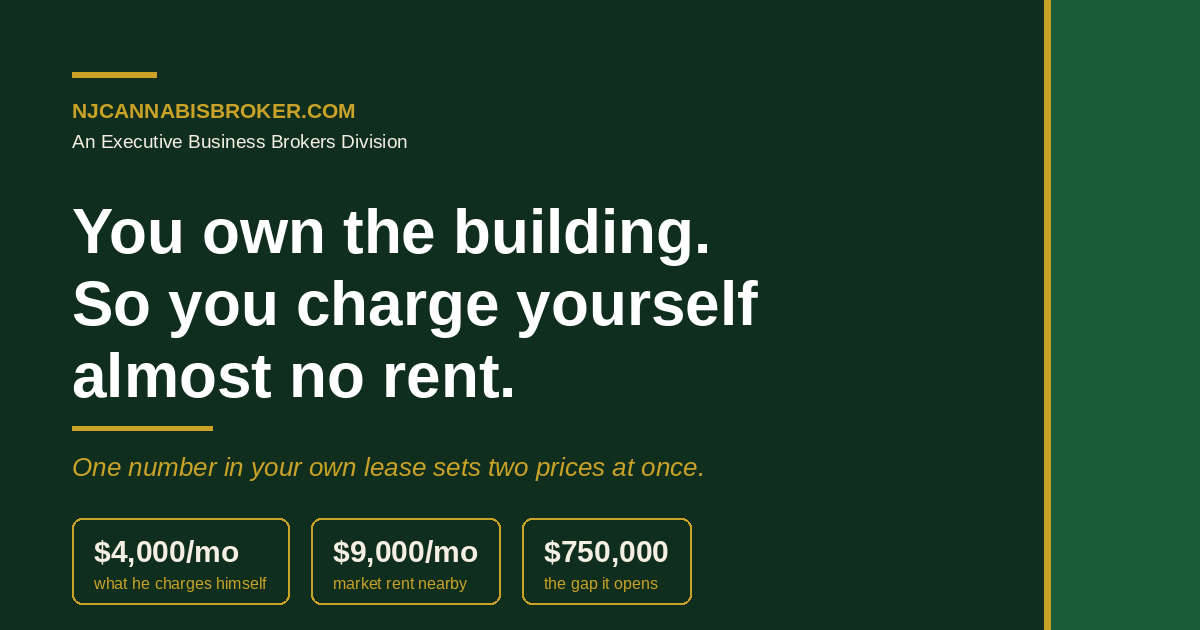
"I own the building, so I only take four thousand a month out of the store."
He said it the way an owner says something he is quietly proud of. No landlord, no escalations, no renewal fight, and four thousand a month of rent he charges himself on a store doing a little under three million a year. That one sentence had already moved two prices in opposite directions, and only one move was in his favor.
The owner is a composite; his figures are mine. Everything around him is real — the asking rents below come from New Jersey listings read this month. Here is what nobody tells an owner-occupier: when you own the store and the roof over it, the rent is a number you invented, and the only input in your deal that sets two prices at once.
Five decisions, in the order they actually arrive. The first one may end the conversation.
1. Are the deed and the license inside the same entity?
Pull the operating agreement and the deed and read whose name is on each. If the license and the real estate sit in one LLC, you do not own two assets. You own one, and this is not your post yet — start with why the license usually decides the structure, because a New Jersey cannabis license cannot be assigned to another party or another premises. An equity sale is usually the only road, and the building rides along inside it.
If the deed sits in a separate holding company and the dispensary is its tenant, you have two assets, two buyers and a real decision. Keep reading.
2. Who set the rent, and what does the lease actually say?
Not what you remember agreeing to. The document. Is there one, is it signed by both entities, what is the term, and is there an assignment clause a buyer can live with?
Then measure your number against the market. On New Jersey dispensary listings this month, asking rents run from $3,500 a month on a Bergen County storefront during its 24-month entitlement period, rising to $9,779 after it, through $6,000 in Somerset County and $9,333 plus NNN in West Milford, up to $14,000 a month on 2,794 square feet in Butler. Against that spread, four thousand dollars is not a rent. It is a bookkeeping entry.
3. What is that rent costing you in federal tax right now?
Most owner-occupiers have never been walked through this. Section 280E denies a plant-touching business its ordinary deductions and leaves it cost of goods sold. A cultivator capitalizes indirect costs into inventory under full absorption, Treas. Reg. 1.471-11. A retailer uses landed cost, 1.471-3(b), and landed cost does not reach the sales floor. An August 2026 practitioner summary puts it flatly: a dispensary cannot reclassify its retail rent as inventory cost.
So the store generally gets no federal deduction for that rent, while the holding company reports every dollar of it as income. New Jersey decoupled from 280E for tax years beginning on or after January 1, 2023, so your state answer and your federal answer are not the same answer. I am a broker, not your CPA. Ask yours what your own rent is doing before you change a word of the lease.
4. What does the roof sell for on its own?
A building net-leased to a licensed operator prices like any other: annual net rent divided by a capitalization rate. Northmarq, writing in June 2026, notes investors may look for cap rates above 10 percent in unlimited-license states, while limited-license markets draw stronger demand and tighter pricing. Run the composite at an illustrative 8 percent.
At $108,000 of market rent, that roof is worth roughly $1,350,000. At the $48,000 he has been charging himself, the same roof prices at $600,000. Same walls, same town, three quarters of a million dollars apart, produced entirely by a figure he typed into a lease he signed with himself. For scale, one West Milford dispensary is currently asking $1,500,000 for the business and the lease, or $2,250,000 with the real estate included. That is an asking price, not a comp.
5. If you keep it, are you willing to be a cannabis landlord?
Keeping the building means your retirement income depends on somebody else's license staying current. Ask what happens if the Commission suspends it, if a notice of violation lands, or if the tenant stops paying in month fourteen — and ask who approves the next assignment, because the lease clause is where these deals die. Price that honestly and you may still prefer being the landlord: a market-rate lease signed by a better-capitalized operator is a sturdier annuity than the one you hold now.
There is a third door. A sale-leaseback sells the real estate to an investor and keeps you in the space on a long primary term — fifteen to twenty years with options and modest annual bumps — and converts roughly 70 to 85 percent of the property's value into cash. It is also one of the few places real capital still reaches this industry.
What you are really deciding is what the lease says
Look at what those five decisions have in common. None is answered on the day you sign a purchase agreement. Every one is answered by a document you either wrote years ago or never wrote at all. Every deal we take to market gets this question asked before the teaser is written.
The owners who get paid for the roof put an arm's-length, market-rate, assignable lease in place twelve to eighteen months before they list, then let it season. The ones who do not are asking a buyer to accept a rent nobody tested. Buyers do not accept it. They re-rent the space at market inside their own model, reprice both halves and hand you the result. And a sale-leaseback needs room: readiness through closing is commonly a ten-to-nineteen-week process, not a phone call.
- The cheque. Sell both: one closing, one price, one allocation to negotiate. Keep it: a smaller cheque and a tenant.
- The rent. Sell both: the buyer sets it in his model anyway. Keep it: you set it now, at market, in writing, and get paid for it twice.
- The tax. Sell both: one event, two allocations, ask your CPA. Keep it: rent income on one return and, federally, usually no deduction on the other.
- The risk. Sell both: your exposure ends at closing. Keep it: your income depends on a license that is not yours.
- The timing. Sell both: one calendar. Keep it, or run a sale-leaseback, and plan in months rather than weeks.
The asset nobody appraises is a sentence in your own lease. I have watched owners spend a year polishing a P&L and never once look at the rent line that was quietly setting half their value, in the wrong direction, the entire time.
You do not have to decide today whether to sell the dirt. You do have to decide what the rent is. Set it at market, put it on paper, let it age, and you will have two assets with two defensible prices instead of one blurred number. Four thousand dollars a month is not thrift. It is a discount you are handing to a buyer you have not met.